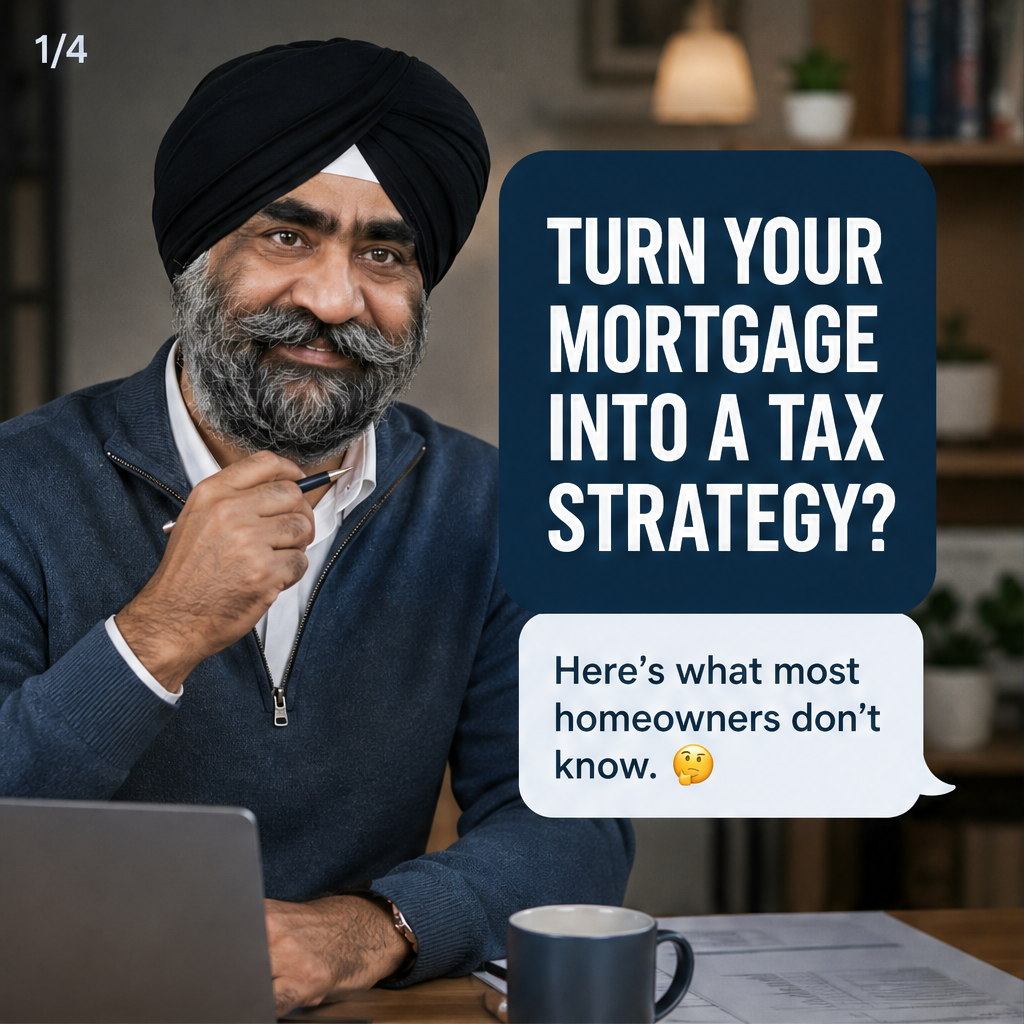
In Canada, mortgage interest on a primary residence is generally not tax-deductible, but the tax treatment can change when borrowed funds are used to earn income or generate investment returns. This carousel explains practical ways to review your mortgage: separate personal and investment borrowing, document the use of funds, and consider strategies such as the Smith Manoeuvre only with qualified advice. Before refinancing or reborrowing, evaluate interest costs, investment risk, cash flow, and CRA requirements. A mortgage professional and tax advisor can help determine whether a proposed structure fits your goals and circumstances.
Continue to full article