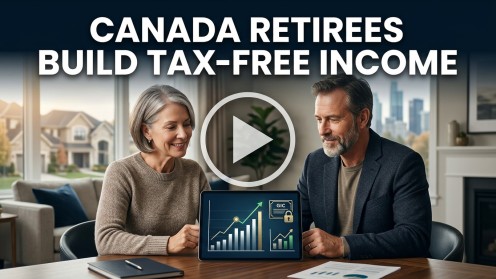
Navigating retirement income in Canada calls for strategies that protect wealth and maximize returns—principles at the heart of my approach to real estate and financial education. By 2026, Canadians with full eligibility have access to $109K each in tax-free account room, allowing retired couples to invest up to $218K for income—without worrying about capital gains, dividends, or interest eating into their pension eligibility above the ~$95K clawback threshold.
For those prioritizing capital preservation, non-cashable GICs offer a secure 3%-4% yield within deposit-insurance limits. Meanwhile, dividend stocks provide more flexibility and often outperform GICs, with the added benefit of growing distributions, though there’s always the consideration of share price movement. The right mix—tailored to individual needs—can see a diversified tax-free account generating around 4% annually, translating to $4.36K per person or $8.72K per couple, entirely tax-free.
As with acquiring undervalued properties, it’s about leveraging every available advantage—from tax shelters to strategic asset selection—to build passive income streams that are resilient and efficient. Thoughtful planning today lays the groundwork for a financially secure tomorrow.