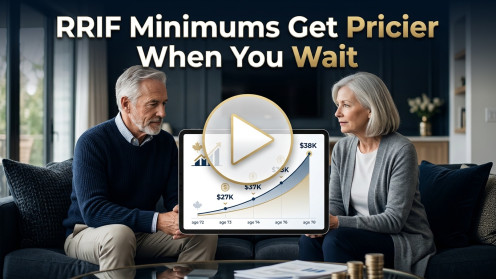
A common pitfall for Canadian investors is underestimating the tax impact of waiting too long to convert an RRSP into a RRIF. By the end of the year you turn 71, your RRSP must transition—often resulting in mandatory withdrawals that are fully taxable. The minimum withdrawal is calculated on your RRIF’s value as of January 1 and increases with age—starting near 5% and climbing to about 20% by age 95. Consider a $500,000 RRSP compounding at 5% annually for seven years: it grows to $704,000, which means, at age 72, your minimum withdrawal jumps to almost $38,000 (compared to $27,000 without that growth). This extra taxable income could push you into a higher bracket, especially when CPP, OAS, workplace pensions, and other investment income kick in—remember, the 2026 OAS recovery tax applies to income above $95,000.
For those who, like my students, approach wealth with a strategic mindset, it pays to plan ahead. Tapping into lower-income years for partial RRSP withdrawals, leveraging pension-income splitting, or using a younger spouse’s age for RRIF setup can help you control when and how much tax you pay. Don’t overlook the power of TFSA contributions to shelter growth. As with real estate investing, deliberate planning and a deep understanding of the rules can unlock significant tax efficiencies—and protect your wealth for the next generation.